Many digital nomads assume they cannot save for retirement while living abroad. Others contribute to an IRA without realizing a common tax election just turned that contribution into an excess contribution. Retirement savings for digital nomads is not actually complicated once you understand one interaction. The Foreign Earned Income Exclusion (FEIE) can reduce your taxable compensation to zero. As a result, zero compensation means zero room for an IRA contribution. This guide walks through the 2026 contribution limits and the rule that trips up self-employed nomads every year.
As of this writing, figures below reflect tax year 2026 limits published by the IRS. However, individual circumstances vary significantly with this topic. Therefore, confirm your specific situation with a CPA who specializes in expat taxes before filing.

Retirement Savings for Digital Nomads: The Rule That Catches People Off Guard
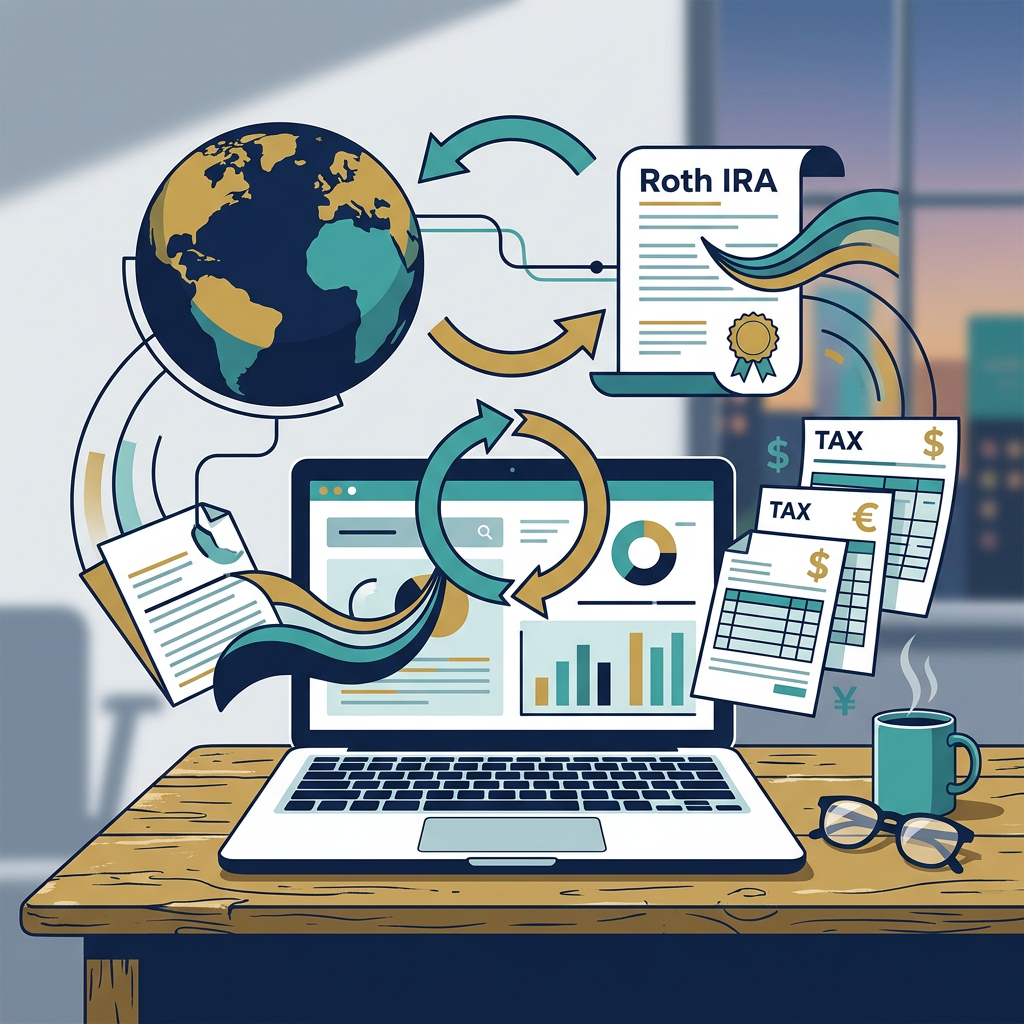
To contribute to a traditional or Roth IRA, the IRS requires taxable compensation, generally wages or self-employment income. However, income excluded from tax through the FEIE does not count as compensation for IRA purposes. As a result, a freelancer who excludes all of their income under the FEIE has $0 of taxable earned income in the eyes of the IRS. This holds true even if they earned well into six figures. Without taxable compensation, an IRA or Roth IRA contribution is not permitted for that year. This comes straight from the IRS’s foreign earned income exclusion guidance.
However, this does not mean nomads are locked out of retirement accounts entirely. Instead, it means your exclusion strategy determines whether you can also fund an IRA in the same year.
Two ways around the trap
The first option is to earn more than the exclusion covers. For tax year 2026, the FEIE covers up to $132,900 of foreign earned income. This is up from $130,000 in 2025, according to the IRS’s 2026 inflation adjustments. For example, if you earn $160,000 and exclude the first $132,900, the remaining $27,100 still counts as taxable compensation. Therefore, that remainder can support an IRA contribution up to the annual limit.
The second option is to claim the Foreign Tax Credit (FTC) instead of the FEIE. The FTC does not exclude your income from US taxation. Instead, it credits foreign taxes you already paid against your US tax bill. Because your income stays classified as taxable compensation, choosing the FTC generally preserves full IRA eligibility. In practice, though, it mainly pays off if you already pay meaningful income tax in your country of residence. Nomads based in low-tax countries, such as several popular Southeast Asia bases, often have little foreign tax to credit. As a result, many still default to the FEIE despite the IRA tradeoff.
2026 contribution limits
For example, assuming you have qualifying compensation, the following limits apply for tax year 2026, per the IRS’s 401(k) and IRA announcement.
| Account | 2026 Limit | Catch-Up (Age 50+) |
|---|---|---|
| 401(k) / 403(b) / Solo 401(k) employee deferral | $24,500 | +$8,000 (ages 50-59, 64+); +$11,250 (ages 60-63) |
| Traditional or Roth IRA | $7,500 | +$1,100 |
One 2026-specific change matters for higher earners. Under SECURE 2.0, catch-up contributions to an employer plan must go into a Roth account if you earned more than $150,000 in FICA wages the prior year. This rule affects W-2 employees more than self-employed nomads, since self-employment income is not FICA wages. Still, it is worth knowing if you split time between remote employment and freelancing.
Roth IRA income limits still apply abroad
Even with qualifying compensation, high earners can be phased out of Roth IRA eligibility entirely. For 2026, the phase-out range runs from $153,000 to $168,000 of modified adjusted gross income for single filers. For married couples filing jointly, it runs from $242,000 to $252,000. Above the top of the range, you cannot contribute directly to a Roth IRA. However, a backdoor Roth conversion may still be available depending on your other accounts. This is a scenario where a cross-border tax advisor earns their fee, since the conversion interacts with foreign tax credits in ways that are easy to get wrong.
Self-employed nomads: Solo 401(k) and SEP IRA
Freelancers and business owners have access to a Solo 401(k) or a SEP IRA. Both allow much larger contributions than a standard IRA. This is because they include an employer contribution component on top of the employee deferral. However, the same FEIE rule still applies. Contributions to these accounts are limited to compensation that was not excluded from tax. A nomad who excludes their full self-employment income under the FEIE therefore faces the same $0 contribution room problem as a W-2 employee. This holds true even though a Solo 401(k) theoretically allows a much higher dollar limit. If you have not yet worked through how the FEIE affects your tax return, our guide on how FEIE really works for US digital nomad taxes covers the mechanics in more depth.
One more wrinkle applies to the SEP IRA specifically. Employer contributions are based on net self-employment earnings after certain deductions. Those calculations still run into the same excluded-income ceiling. For instance, a consultant who nets $90,000 and excludes all of it under the FEIE has no remaining net earnings to base a SEP contribution on. This holds true regardless of the plan’s normally generous limits. In addition, state-level rules can differ from federal ones. Therefore, nomads who still file a state tax return should check whether their state recognizes the FEIE the same way the IRS does.
An actionable approach for this tax year
Before year-end, estimate your total foreign earned income and compare it against the $132,900 exclusion threshold. For example, if you are well under it and want to keep saving in a US retirement account, consider a smaller partial exclusion or the FTC for the year. Either approach preserves taxable compensation you can contribute against. If that tradeoff is not worth it for your tax bill, a taxable brokerage account remains a straightforward alternative. For options on investing without a fixed US address, see our guide on digital nomad investing with no fixed address.

Frequently Asked Questions
Can I contribute to a Roth IRA if I use the Foreign Earned Income Exclusion?
You can generally contribute up to the amount of compensation that was not excluded under the FEIE. However, if you exclude all of your income and have no other taxable compensation, you cannot contribute to a Roth IRA for that tax year.
Is a Solo 401(k) better than an IRA for a self-employed nomad?
A Solo 401(k) generally allows a much higher contribution limit than an IRA, since it includes both an employee and employer contribution component. However, it does not bypass the FEIE compensation rule. Therefore, the benefit mainly shows up when you have taxable compensation available to contribute.
Does the Foreign Tax Credit generally work better than the FEIE for nomads?
Not necessarily. The Foreign Tax Credit tends to help more when you already pay meaningful income tax in your country of residence. It also preserves your IRA eligibility. In contrast, nomads based in low-tax or zero-tax countries often save more overall with the FEIE, even accounting for the lost IRA contribution room. Therefore, the better choice depends on your specific tax situation and should be modeled out with a tax professional.
Related Reads
- US Digital Nomad Taxes 2026: How FEIE Really Works — the exclusion that decides how much IRA contribution room you actually have
- Digital Nomad Tax Residency: The 183-Day Rule Explained — how your day count affects taxes beyond retirement accounts
- Digital Nomad Investing: How to Invest With No Fixed Address — where to put savings once your IRA room runs out
Sources
Therefore, contribution limits and exclusion amounts here come directly from the IRS newsroom announcement on 2026 401(k) and IRA limits, the IRS 2026 tax inflation adjustments release, and the IRS Foreign Earned Income Exclusion page. This article is educational information, not personalized tax advice, so consult a licensed tax professional for your specific situation.